
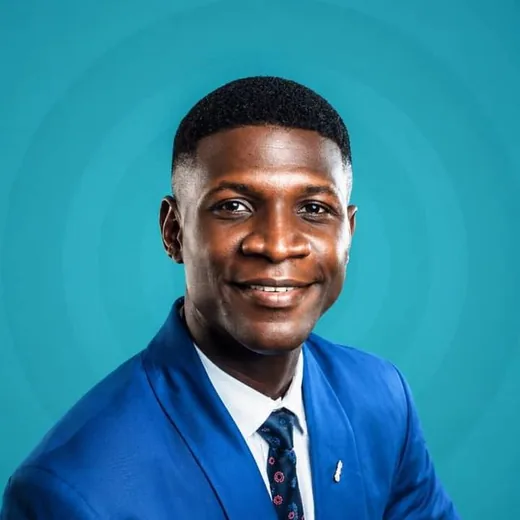
Dikeocha Precious
CEO & Co-Founder
Carries the vision, and the responsibility of turning the idea into something real.
Millions of Nigerians are locked out of digital money because it assumes a smartphone, an account number and a signal. CASAIPAY replaces all three with the one thing everybody already has.
A working prototype, not a mockup. Nothing you enter leaves your device.
 Welcome back,Chidi Okafor
Moniepoint, OPay, Paystack and Flutterwave already move money brilliantly. CASAIPAY asks a different question — and sits between two that nobody has answered together.
“Can I trust this customer?”
“Can I reach my money when I need it?”
We are not building because fintech is growing. We are building because there is still a gap between institutions and millions of people — especially in informal economies where traditional systems struggle. That makes CASAIPAY an infrastructure layer the ecosystem plugs into, not one more app competing for the same transactions.
Money can be sent to someone who has never opened a bank account, and collected in cash from a shop down the road.
The sender enters a name and links a biometric identity. No account number needed.
The transfer is initiated exactly like any other payment.
CASAIPAY binds the payment to the recipient's biometric profile, not to an account.
The recipient visits any CASAIPAY agent with their personal code.
Verification happens on the agent's ordinary Android phone. No special hardware.
And a CASAIPAY ID is issued, opening the door to savings, credit and insurance.
Face and fingerprint replace account numbers, debit cards and smartphones. Who you are becomes the credential.
Funds move to a verified identity rather than an account, so a recipient can be paid before they have ever opened one.
Trusted local shops become verification, onboarding and cash-out points. The agent's existing Android phone is the terminal — no hardware to buy.
Identity verification, fraud detection, routing to the nearest agent, and clean integration with partner banks and licensed providers.
Cameras fail in bad light. People get watched at the counter. Sometimes a person is not paying by choice. Each of these is a design problem, and each has an answer built in.
Face ID alone, face plus passcode, or either one. A cracked lens or a dark stall shouldn't stop somebody buying rice.
Passcode digits move position after every tap, so watching somebody's fingers across a counter reveals nothing.
A second passcode — or a deliberate expression — opens the account showing a smaller balance you set. The payment completes, the real money stays put, and help is alerted quietly.
Identity is the foundation, but nobody adopts infrastructure. They adopt something useful. So the wallet handles the bills a Nigerian household actually pays.
From ₦100
Token on receipt
All four networks
Domestic routes
A customer arrives with no cash and no card. The shop asks for a CASAIPAY ID, types the amount, and hands over the phone. The customer's face approves it and the money lands.
Concept and prototype are done. The MVP is in build. Everything after that depends on this round, so it's framed by what the money unlocks rather than by calendar dates.
Product, brand and go-to-market defined. CAC registration secured.
A working end-to-end demo of registration, verification and the payment flow.
Real-time build, biometric infrastructure, and the start of the CBN pathway.
First agent network live, first real transactions, first evidence for a Series A.
Carries the vision, and the responsibility of turning the idea into something real.
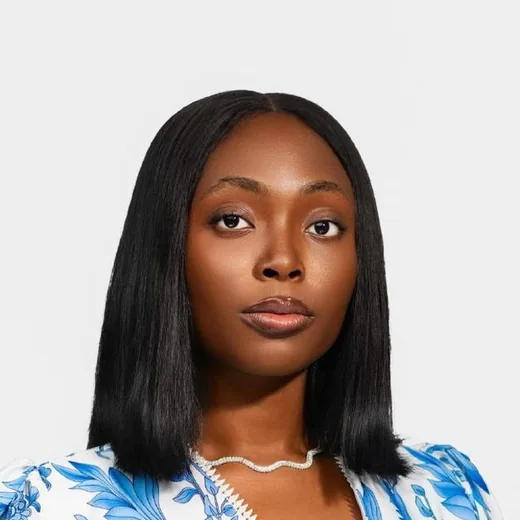
Shapes the company, challenges the vision, and turns big ideas into something executable.
Translates the vision into technology that actually works at scale.
Let people receive money using their identity instead of an account number, and you change how millions of underserved Africans take part in the financial system.